
If you’re thinking about buying a home in Portsmouth, Rye, Dover, Exeter, Greenland, Stratham, elsewhere on the New Hampshire Seacoast, or Southern Maine, you may be asking the same question we hear from many buyers:
Should I wait for mortgage rates to come down before I buy?
It’s a reasonable question. A lower mortgage rate can reduce your monthly payment and increase your buying power.

But buyers waiting for rates to fall dramatically should understand something that’s happening behind the scenes in the mortgage market. It’s called the mortgage spread, and right now it may tell us more about where mortgage rates could go than many buyers realize.
Mortgage Rates and the 10-Year Treasury Yield
Mortgage rates don’t move independently. Historically, the 30-year fixed mortgage rate has tended to track the yield on the 10-year U.S. Treasury note.
They aren’t identical, and they don’t move point-for-point every day. Inflation expectations, economic growth, Federal Reserve policy, investor demand for mortgage-backed securities, market volatility, and other factors can all influence mortgage rates.
But over more than 50 years, the relationship between the 10-year Treasury yield and 30-year mortgage rates has been remarkably consistent.

The difference between the mortgage rate and the 10-year Treasury yield is known as the spread.
Historically, that spread has averaged approximately 1.76 percentage points.
That matters because, in simplified terms:
10-Year Treasury Yield + Mortgage Spread ≈ 30-Year Mortgage Rate
The size of that spread can therefore significantly impact what homebuyers actually pay for a mortgage.
Why Mortgage Rates Rose So Much in 2023
During periods of economic and financial uncertainty, the mortgage spread can widen.
That’s exactly what happened in 2023.
At one point, the spread between mortgage rates and the 10-year Treasury yield reached approximately 3.19 percentage points — far above its long-term historical average.
That unusually wide spread was one of the reasons mortgage rates climbed so high.

Since then, something important has happened.
The spread has narrowed considerably.
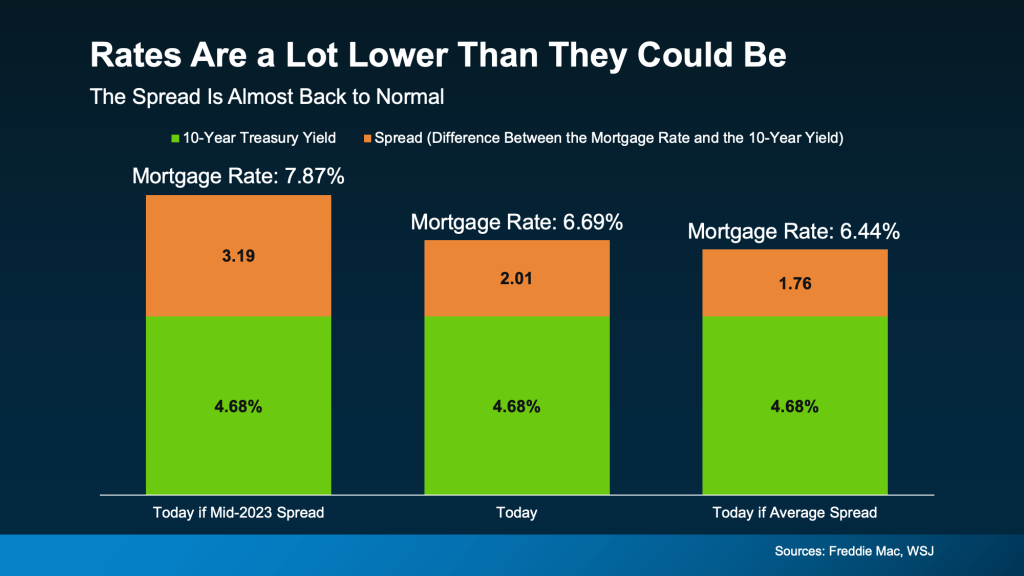
Recent data in the accompanying charts show the spread at approximately 2.01 percentage points, much closer to its historical average of 1.76.
That’s good news for today’s homebuyers.
Mortgage Rates Are Actually Lower Than They Could Be
Consider the example illustrated in the chart.
With a 10-year Treasury yield of approximately 4.68%:
- Using the unusually wide 3.19-point spread seen in 2023 would produce a mortgage rate of roughly 7.87%.
- With a spread of approximately 2.01 points, the mortgage rate would be around 6.69%.
- At the historical average spread of 1.76 points, the mortgage rate would be approximately 6.44%.
That’s an important distinction.
The narrowing spread has already provided meaningful relief to mortgage borrowers. Without that improvement, mortgage rates could be considerably higher.
But there’s another side to the story.
Why Waiting for a Dramatic Mortgage-Rate Drop Could Be Risky
Because the mortgage spread has already moved much closer to normal, there may be less room for mortgage rates to decline simply because the spread continues narrowing.
For rates to fall substantially from here, we’d likely need help from other factors — particularly a decline in the 10-year Treasury yield.
That could happen if inflation cools, economic growth slows, investor expectations change, or other economic conditions push Treasury yields lower.
But no one can reliably predict exactly when that will happen or how large the decline will be.
That’s why trying to perfectly time mortgage rates can be difficult.
For buyers in Portsmouth and across the New Hampshire Seacoast, there’s another factor to consider: while you’re waiting for a lower rate, the housing market isn’t standing still.

What This Means for Portsmouth and New Hampshire Seacoast Homebuyers
Real estate is local.
The decision to buy shouldn’t be based on mortgage rates alone. Buyers also need to consider home prices, available inventory, competition, negotiating leverage, their expected length of ownership, and their personal financial situation.
This is particularly important in communities such as Portsmouth, Rye, Greenland, Stratham, Dover, and Exeter, where desirable properties can face limited inventory.
Waiting for a substantially lower mortgage rate doesn’t necessarily mean you’ll get a better overall deal.
For example, suppose rates decline but more buyers return to the market at the same time. Increased demand could mean:
more competition → fewer negotiating opportunities → stronger offers → potentially higher home prices.
A lower rate is certainly valuable, but it’s only one part of the homebuying equation.
What About Southern Maine?
Buyers looking across the state line in Kittery, York, Eliot, South Berwick, and other Southern Maine communities face many of the same considerations.
Inventory, location, property taxes, insurance costs, condition, proximity to the coast, and individual financing options can have as much impact on the overall affordability of a home as a modest change in mortgage rates.
That’s why we encourage buyers to look at the entire financial picture, rather than choosing an arbitrary mortgage rate and waiting for the market to reach it.
A Small Change in Rates Can Still Matter
None of this means mortgage rates don’t matter.
They absolutely do.
Even a quarter-point or half-point difference can affect a monthly mortgage payment, particularly on higher-priced homes.
But there are several ways buyers can approach today’s market.
Depending on the property and transaction, you may be able to negotiate a seller credit toward closing costs or an interest-rate buydown. Different loan programs may offer different rates and costs. Buyers can also purchase when they find the right home and potentially refinance later if rates decline enough to make refinancing financially worthwhile.
The right strategy depends on the buyer, the property, the financing, and current market conditions.
Should You Buy a Home Now or Wait?
Instead of asking:
“When will mortgage rates come down?”
A better question may be:
“Would buying the right home at today’s price and today’s rate make financial sense for me?”
If the answer is yes, waiting solely for a dramatically lower mortgage rate may not be the best strategy.
If the numbers don’t work, waiting may be entirely appropriate.
There isn’t one answer for every buyer.
That’s especially true in the New Hampshire Seacoast and Southern Maine, where housing markets can vary considerably from one community — and even one neighborhood — to another.
The Bottom Line
Mortgage rates aren’t as low as buyers would like, but the narrowing spread between mortgage rates and the 10-year Treasury yield means rates are already considerably better than they might otherwise be.
At the same time, because the spread has moved closer to its historical norm, buyers shouldn’t automatically assume there’s a huge rate decline waiting just around the corner.
If you’re considering buying in Portsmouth, Rye, Greenland, Stratham, Dover, Exeter, the New Hampshire Seacoast, or Southern Maine, we’d be happy to help you look beyond the headlines and evaluate the actual numbers.
Sometimes waiting makes sense.
Sometimes the better opportunity is finding the right property, negotiating the best possible terms, and making the move when the numbers work for you.
Interested in finding out what works best for you? Give us a call or email, and let’s sit down and talk. No cost, no obligation, and no pressure, just the facts.

Frequently Asked Questions About Mortgage Rates and Buying a Home on the New Hampshire Seacoast
1. Will mortgage rates go down in 2026?
Mortgage rates can move up or down based on Treasury yields, inflation, economic conditions, investor expectations, and the mortgage spread. Rates could decline, but buyers should be cautious about making a home purchase strategy dependent on a large or rapid drop that may not occur.
2. What is the mortgage spread?
The mortgage spread is the difference between the interest rate on a mortgage and the yield on the 10-year U.S. Treasury note. Historically, that difference has averaged roughly 1.76 percentage points, although it can be significantly wider or narrower at different times.
3. Why does the 10-year Treasury affect mortgage rates?
Mortgage-backed securities compete with Treasury securities for investors. As Treasury yields change, the returns investors require from mortgage-backed securities generally change as well. That’s one reason 30-year mortgage rates tend to move with the 10-year Treasury yield.
4. Should I wait for mortgage rates to fall before buying a home in Portsmouth, NH?
Not necessarily. Consider the home’s price, monthly payment, available inventory, competition, your expected time in the home, and your overall finances. Waiting for a lower rate could help, but you could also encounter higher prices or increased buyer competition later.
5. Is now a good time to buy a home on the New Hampshire Seacoast?
It depends on your individual circumstances. For financially prepared buyers who expect to remain in the area for several years and can comfortably afford today’s payment, opportunities may exist now. The analysis should be specific to the property and community you’re considering.
6. What happens to Portsmouth-area home prices if mortgage rates fall?
Lower rates generally improve affordability and can bring additional buyers into the market. In an inventory-constrained market, increased demand can potentially put upward pressure on prices. A lower mortgage rate therefore doesn’t automatically mean a lower overall cost to purchase a home.
7. Can I buy now and refinance if mortgage rates fall?
Potentially. Homeowners commonly refinance when rates fall enough to justify the closing costs and other expenses associated with a new loan. However, refinancing is never guaranteed, so buyers should be comfortable with the mortgage they’re accepting when they purchase.
8. Can a seller help buy down my mortgage rate?
Sometimes. Depending on the loan program, contract terms, and market conditions, a seller may agree to provide concessions that a buyer can apply toward allowable closing costs or a mortgage-rate buydown. Your lender and REALTOR® can help determine what is permitted and whether it makes financial sense.
9. Are the housing markets in Portsmouth, Rye, Dover, Exeter, Greenland, and Stratham the same?
No. Even neighboring Seacoast communities can have meaningful differences in home prices, inventory, property types, taxes, buyer demand, and days on market. That’s why broad national housing headlines aren’t enough when making a local real estate decision.
10. Is buying in Southern Maine different from buying on the New Hampshire Seacoast?
Yes. Buyers considering communities such as Kittery, York, Eliot, and South Berwick should compare property taxes, insurance, state-specific closing practices, inventory, commuting considerations, and other ownership costs in addition to the purchase price and mortgage rate.
Looking for a Home on the New Hampshire Seacoast or in Southern Maine?
Jim Lee & Ann Cummings, REALTORS®
RE/MAX Shoreline
Serving homebuyers and sellers throughout Portsmouth, Rye, New Castle, Greenland, Stratham, Dover, Exeter, Hampton, the New Hampshire Seacoast, Kittery, York, and Southern Maine.
Two experienced REALTORS® working together to help you make a well-informed real estate decision.